Long-Term Care Awareness Month: Is Your Retirement Plan Prepared for the Unexpected?
Retirement planning often focuses on the milestones people look forward to most: leaving the workforce, traveling, spending more time with family, and enjoying the financial freedom built over decades of hard work. But a comprehensive retirement strategy also needs to account for the possibilities that are less comfortable to consider.
One of those possibilities is long-term care.
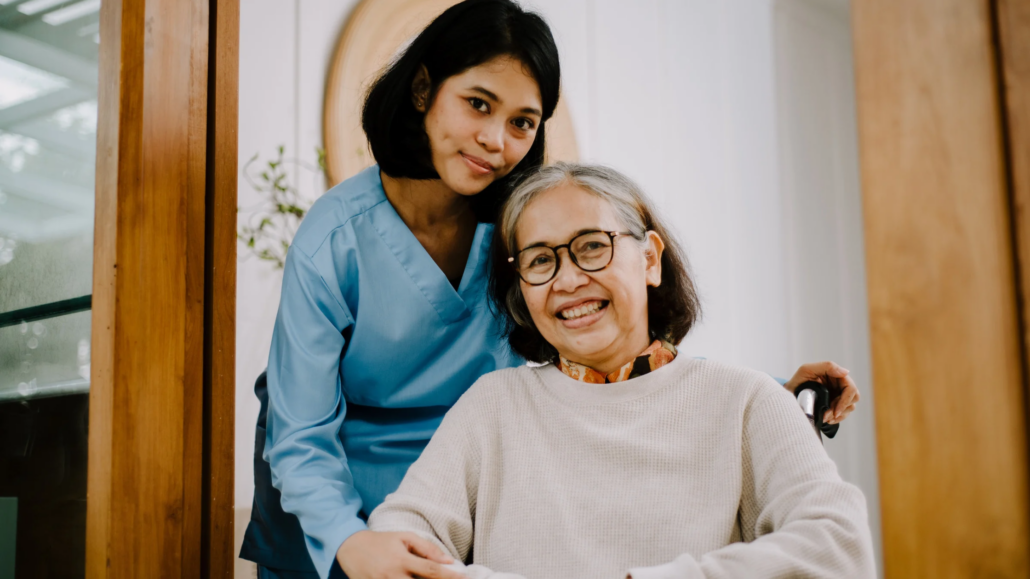
As people age, they may eventually need assistance with everyday activities, ongoing supervision, or specialized care at home or in a residential facility. These needs can arise gradually or following an unexpected illness, injury, or change in health. Regardless of when they occur, the associated expenses may affect retirement income, savings, and long-term financial goals.
November’s Long-Term Care Awareness Month offers an opportunity to take a closer look at this often-overlooked aspect of retirement preparedness. While no one can predict exactly what care they may need in the future, understanding the financial implications and evaluating available options can help individuals and families make more informed decisions.
At Agemy Financial Strategies, we believe in planning instead of predicting. Preparing for potential long-term care needs is one way to apply that philosophy to the realities of retirement.
What Is Long-Term Care, and Who Might Need It?
Long-term care refers to a range of services that help individuals manage chronic illnesses, disabilities, or age-related limitations when they need assistance with everyday activities. Unlike treatment intended to address a specific medical condition, long-term care often focuses on helping someone maintain daily routines, independence, safety, and quality of life.
Depending on an individual’s circumstances, care may include assistance with:
- Activities of daily living: Bathing, dressing, eating, using the bathroom, and moving around safely.
- Household responsibilities: Preparing meals, shopping, cleaning, and managing everyday tasks.
- Supervision and personal support: Assistance for individuals who have cognitive impairments or require ongoing monitoring.
- Specialized care: Support provided by trained caregivers or professionals in a home, community, assisted living, or nursing home setting.
Long-term care is not exclusively a concern for people in their eighties or nineties. An accident, chronic illness, or other unexpected health event can create care needs earlier in life.
It is also important to recognize that needing assistance does not necessarily mean moving into a nursing home. Some people receive care in their own homes, while others use adult day services, assisted living communities, or nursing facilities.
The appropriate setting depends on the individual’s needs, preferences, available support, and financial circumstances.
Because the timing, duration, and type of care can vary considerably, it is difficult to estimate future costs with precision. That uncertainty is precisely why long-term care deserves a place in retirement planning conversations.
Why Long-Term Care Matters to Your Retirement Plan
Many retirement plans are built around predictable categories of spending, including housing, food, transportation, travel, taxes, and routine healthcare expenses. Long-term care can introduce a different financial challenge because its cost and duration may be difficult to anticipate.
For some households, an extended period of care could represent a significant additional expense. For others, existing resources, insurance coverage, or family support may help address some of the need.
The important consideration is how a potential care expense could affect the rest of a financial plan.
1. Long-Term Care Could Affect Retirement Income
Retirement often involves transitioning from a regular paycheck to income generated by Social Security, pensions, retirement account distributions, investments, and other resources.
A long-term care expense may require additional withdrawals from those resources. Depending on the amount, duration, and timing of the expense, those withdrawals could affect how much remains available for everyday living, travel, charitable giving, or other priorities.
For example, a household that expects to use a portion of its savings to supplement monthly retirement income may need to reconsider that approach if substantial care expenses arise.
This does not mean that a long-term care event will necessarily derail a retirement plan. It means that the possibility should be considered when evaluating how much income and liquidity may be needed over time.
2. Unexpected Costs Could Put Pressure on Savings
Retirement savings are generally intended to support expenses over many years. A large, unplanned expense can change the pace at which those assets are used.
The effect depends on several factors, including the household’s available resources, other income sources, insurance coverage, investment performance, and the amount spent on care.
It is also important to consider when the expense occurs. If investments must be sold to cover care costs during a period of market declines, withdrawals could compound the pressure on a portfolio.
No investment allocation or withdrawal strategy can eliminate this risk. However, examining how a retirement plan might respond to different expense scenarios can help identify potential vulnerabilities before a financial decision becomes urgent.
3. Long-Term Care May Affect a Spouse or Other Family Members
Long-term care planning is not solely about the person receiving care. It can also affect a spouse, partner, adult children, and other family members who may provide financial or personal support.
A spouse may need to manage household expenses with fewer available resources. Adult children may need to balance caregiving responsibilities with employment, their own families, and personal financial goals.
Family members may also face decisions about whether paid care, in-home assistance, or a residential setting is appropriate.
Discussing these possibilities in advance can help families understand one another’s expectations, preferences, and limitations. It may also help reduce the likelihood that decisions must be made without sufficient time to evaluate the available options.
Does Medicare Cover Long-Term Care?
One of the most important misconceptions to address is the assumption that Medicare will pay for long-term care simply because someone is retired or eligible for Medicare benefits.
Medicare generally does not cover long-term custodial care. This includes many services that help with daily activities, whether those services are provided at home, in an assisted living setting, or in a nursing home.
Medicare may cover certain medically necessary skilled nursing or rehabilitation services under specific conditions. However, this coverage is different from paying for ongoing assistance with everyday activities.
Medicare Supplement Insurance, commonly called Medigap, generally does not cover long-term custodial care either.
Medicaid may cover certain long-term care services for eligible individuals, subject to applicable federal and state requirements. Eligibility rules, covered services, and financial criteria vary, and individuals should understand how these rules apply to their circumstances before making decisions about their assets.
Private long-term care insurance is another potential source of funding, depending on the policy’s terms and whether its benefit requirements are satisfied.
Understanding what existing coverage does and does not provide is an important starting point. Without that review, a retirement plan may rely on benefits that are not available for the services a person ultimately needs.
Source: Medicare.gov, Long-Term Care and Nursing Home Care coverage information.
How Much Could Long-Term Care Cost?
The cost of long-term care varies based on the type of service, location, provider, frequency of care, and duration of assistance. In-home care, assisted living, and nursing home care can have substantially different costs, and expenses may change over time.
For example, receiving a few hours of assistance at home each week creates a different financial obligation than paying for daily support or a residential setting that provides more extensive care.
Geographic location also matters. Care costs in one community may differ considerably from those in another, making national averages an imperfect estimate of what a particular household might pay.
Inflation is another consideration. If care is needed years from now, today’s prices may not accurately reflect future expenses. At the same time, the amount and type of care required cannot be known in advance.
Rather than relying on a single estimate, consider evaluating several hypothetical scenarios:
- Limited support: What if you need occasional assistance with household tasks or personal care?
- Ongoing in-home care: How might your finances change if you need paid assistance several days a week?
- Extended care: What if you need more comprehensive support for several years?
- Care for both spouses: How would your financial plan respond if you and your spouse needed care at different times?
These scenarios are not predictions. They are planning exercises that can help you evaluate how different expenses might interact with your income, savings, and other retirement priorities.
For current cost information, the U.S. Department of Health and Human Services’ LongTermCare.gov resources and state-specific resources can provide a useful starting point.
What Are Your Options for Paying for Long-Term Care?
There is no single funding approach that works for every household. The appropriate options depend on available assets, income, age, health, insurability, family circumstances, and personal preferences.
Understanding the alternatives can help you identify questions to address within your broader retirement strategy.
1. Self-Funding Through Savings and Investments
Some individuals plan to pay for potential long-term care expenses using their existing financial resources. These may include cash reserves, taxable investment accounts, retirement accounts, or other assets.
Self-funding offers flexibility because there is no insurance policy’s benefit structure to navigate. However, it also means the household is responsible for covered expenses and any associated financial consequences.
Before relying on this approach, consider how much of your assets could reasonably be allocated to potential care expenses without undermining other priorities.
For example, funds designated for long-term care may otherwise be needed for regular retirement income, a surviving spouse’s financial security, charitable giving, or a planned inheritance.
A financial plan can help evaluate these competing objectives and examine how different spending scenarios might affect the overall picture.
2. Traditional Long-Term Care Insurance
Traditional long-term care insurance is designed to help pay for qualifying long-term care services when the policy’s benefit requirements are met.
Depending on the contract, a policy may cover eligible services received at home, in an assisted living community, or in a nursing facility. Benefits, elimination periods, coverage limits, inflation protection, exclusions, and other provisions vary by policy.
Premiums and eligibility also depend on factors such as age, health history, and the insurer’s underwriting standards.
It is important to understand that purchasing coverage does not eliminate every financial risk. Policies may have daily or monthly benefit limits, maximum benefit periods, and other restrictions. Premiums may also increase under certain circumstances, subject to applicable law and policy provisions.
Before purchasing a policy, review its terms carefully and compare the potential benefits with the premiums, limitations, and your ability to maintain payments over time. An appropriately licensed insurance professional can help explain the available contracts.
3. Hybrid Life Insurance and Long-Term Care Products
Some insurance products combine life insurance with long-term care benefits. Depending on the contract, qualifying care expenses may be funded through an acceleration of the life insurance death benefit or through additional benefits attached to the policy.
These arrangements may appeal to people who want to address more than one financial objective with a single product.
However, hybrid policies differ substantially in their structure, costs, benefit limits, funding requirements, and treatment of any remaining death benefit. Some require a substantial initial premium or a series of payments.
It is important to evaluate the product in the context of your broader financial plan rather than assuming that a hybrid policy is automatically preferable to traditional coverage or self-funding.
Reviewing the contract with qualified insurance and financial professionals can help clarify how the product works and whether its features align with your objectives.
4. Government Programs and Other Resources
Medicaid may help provide assistance with qualifying long-term care expenses for people who meet applicable eligibility requirements. Those requirements differ by state and may involve income, assets, medical need, and other criteria.
Eligibility rules can be complex, particularly for married individuals or households considering transfers of assets. Decisions made without understanding the relevant rules may have unintended consequences.
If Medicaid may become part of your planning considerations, consult a qualified elder law attorney or other appropriate professional before making asset transfers or significant financial changes.
Family caregiving, community programs, veterans’ benefits for eligible individuals, and other local resources may also play a role, depending on the circumstances. Availability and eligibility should be verified rather than assumed.
The objective is to understand the range of potential resources and how they may fit together.
When Should You Start Planning for Long-Term Care?
It is easy to postpone long-term care discussions when care does not seem immediately relevant. However, waiting until assistance is needed may limit the time available to evaluate options.
For insurance, age and health can affect eligibility, underwriting, premiums, and the terms available. Applying does not guarantee approval, and a policy’s benefits may be subject to waiting periods and other requirements.
Starting the conversation earlier can provide more time to compare coverage, evaluate costs, and consider how potential expenses fit into a long-term financial strategy.
That does not mean everyone needs to purchase insurance at a particular age. Some households may be better positioned to self-fund certain expenses, while others may want to explore transferring a portion of the financial risk through insurance.
The decision should reflect individual circumstances rather than a universal rule.
If you are approaching retirement, already retired, or reviewing your financial plan after a major life change, consider whether long-term care assumptions have been addressed.
A review can help identify gaps, clarify priorities, and determine whether additional analysis is appropriate.
Five Questions to Ask About Your Long-Term Care Plan
Long-Term Care Awareness Month provides a natural opportunity to assess how prepared you are for potential future care needs.
Consider the following questions as a starting point.
- Have I estimated potential care expenses?
Review the costs associated with different types of care in the locations where you might realistically receive services. Consider how those expenses could change over time.
- Do I understand what my existing insurance covers?
Review your health insurance, Medicare benefits, any long-term care policy, and other relevant coverage. Confirm the conditions, limits, and exclusions that apply.
- Could my retirement income support additional expenses?
Consider how care costs might affect withdrawals from your retirement accounts, investment assets, and other income sources. Examine how different scenarios could influence your financial priorities.
- Have I discussed my preferences with my family?
Think about where you would prefer to receive care, who might be involved in decisions, and how you would communicate your wishes. These conversations can be uncomfortable, but they may help your family understand your priorities before a decision becomes urgent.
- Are my legal and financial documents current?
Review your estate planning documents, healthcare directives, powers of attorney, and beneficiary designations as appropriate. A qualified attorney can help determine which documents may be relevant and whether updates are warranted.
These questions are not intended to predict your future needs. They are designed to help you identify areas where more information or planning may be useful.
Integrating Long-Term Care Into Your Retirement Strategy
Long-term care planning should not happen in isolation from the rest of your financial life.
The potential costs of care may interact with retirement income, investment decisions, taxes, insurance, and estate planning. Looking at these areas together can help you understand the trade-offs associated with different approaches.
For example, setting aside assets for potential care expenses may affect the amount available for other goals. Purchasing insurance introduces premium costs that must be considered alongside existing retirement expenses. Depending on the policy, benefits may help offset certain care costs, but coverage limits and eligibility requirements remain important.
Tax considerations also deserve attention. The tax treatment of insurance benefits, retirement account distributions, and other funding sources can depend on the specific circumstances and applicable law. A qualified tax professional can help evaluate those implications.
A coordinated review may include:
- Assessing current retirement income sources and projected expenses.
- Evaluating available savings and liquidity for unexpected costs.
- Reviewing existing insurance coverage and potential gaps.
- Considering how different care-cost scenarios could affect a retirement portfolio.
- Coordinating long-term care considerations with estate planning objectives.
- Revisiting assumptions as financial circumstances, family needs, and applicable rules change.
No strategy can eliminate every uncertainty or guarantee a particular outcome. The purpose of this process is to understand the available choices, evaluate potential risks, and make decisions that reflect your priorities.
Plan for the Unexpected With Agemy Financial Strategies
A thoughtful retirement plan considers more than the income you expect to receive and the expenses you anticipate paying. It also recognizes that life can introduce circumstances that are difficult to forecast.
Long-term care is one such possibility. Although no one can know precisely what their future care needs will be, preparing for different scenarios can help individuals and families approach these decisions with greater clarity.
At Agemy Financial Strategies, we believe in planning instead of predicting. Our approach to retirement planning considers the broader financial picture, including income needs, investment management, tax considerations, and long-term financial objectives.
Long-Term Care Awareness Month is an opportunity to ask whether your current strategy accounts for potential care expenses and whether your assumptions still reflect your circumstances.
If you would like to review your retirement strategy, visit agemy.com to learn more about our services and connect with our team.
Preparing for the unexpected begins with understanding your options today.
Important Disclosure
This article is provided for informational and educational purposes only and should not be construed as individualized investment, financial, tax, insurance, or legal advice, or as a recommendation to buy or sell any security, purchase any insurance product, or adopt any particular investment strategy. The information presented is general in nature and may not be appropriate for every individual or situation. Insurance products, coverage, eligibility, costs, and benefits vary by policy and provider. Government program eligibility and coverage are subject to applicable laws and regulations, which may change. Consult qualified financial, insurance, tax, and legal professionals regarding your specific circumstances before making financial decisions.
All investing involves risk, including the possible loss of principal. No investment strategy can guarantee a profit or protect against loss in all market conditions. Past performance is not indicative of future results.
Investment advisory services are offered through Agemy Wealth Advisors, LLC, a Registered Investment Adviser and fiduciary to its advisory clients. Agemy Financial Strategies, Inc. is a franchisee of Retirement Income Source®, LLC. Agemy Financial Strategies, Inc. and Agemy Wealth Advisors, LLC are affiliated entities and are not affiliated with Retirement Income Source®, LLC.